Centre for Inclusive Trade Policy home page
Briefing Paper
The Jobs in Trade Database: Novel data on exporting firms and their employees
Black, J; Fox, C; Spowage, M. (2026) The Jobs in Trade Database: Novel data on exporting firms and their employees, CITP Briefing Paper 34
Published 15 September 2026
CITP Briefing Paper 34
Key points
- Trade is often discussed as an abstract economic concept, but its impacts are felt through people, places and firms.
- Concerns about the winners and losers from trade have made it increasingly important to look beyond simple trading metrics.
- The Jobs in Trade Database provides a new evidence base for examining some of these links by separating selected business and employee indicators by industry, year and organisation export status.
- The database was produced by linking government microdata in the ONS Secure Research Service, allowing us to classify firms on an annual basis as exporters or non-exporters and connect these classifications to both firm-level economic indicators and employee-level records.
- This is a unique contribution to the UK evidence base because it allows users to compare the exporting and non-exporting parts of industries at a granular level, while also breaking down employee jobs by characteristics such as sex, age, skill group and earnings.
- The data allows users to look beyond industry averages and examine how exporting activity is associated with different types of firms and different groups of workers.
- In 2022, around 31% of full-time equivalent employee jobs with known export status in Great Britain worked for exporting organisations while 69% worked for non-exporting organisations.
- Men were more likely to have jobs in exporting organisations than women, with differences appearing to be strongly related to industry. However, trends over time do not always favour male workers, with male jobs in manufacturing exporters appearing to have fallen between 2015 and 2022.
- Jobs in exporting organisations were associated with higher median hourly earnings. In 2022, median hourly earnings were £16.05 per hour for exporting jobs compared with £13.87 for non-exporting jobs, a premium of 15.7%. The wage premium was higher for those aged 30+ compared to those aged 16-29, and higher for skilled occupations compared to less skilled occupations.
- Exporting firms accounted for 50.8% of output and 47.0% of Gross Value Added in Great Britain while employing under a third of full-time equivalent employee jobs, reflecting substantially higher labour productivity.
- The dataset, methodology and user guide1 can be accessed via the UK Data Service ReShare repository.
Acknowledgements and data access
Data access: The results of our research are publicly available under a CC By license via the UK Data Service ReShare repository (DOI: 10.5255/UKDA-SN-858696). These were produced using the datasets listed in the endnotes.
This work was conducted by members of the Centre for Inclusive Trade Policy, supported by the ESRC [grant number ES/W002434/1].
The analysis was carried out in the Secure Research Service, part of the Office for National Statistics. This work contains statistical data from ONS which is Crown Copyright. The use of the ONS statistical data in this work does not imply the endorsement of the ONS in relation to the interpretation or analysis of the statistical data. This work uses research datasets which may not exactly reproduce National Statistics aggregates.
Introduction
Trade is often discussed as an abstract economic concept, but its impacts are felt through firms, jobs, wages and supply chains. Concerns about the distribution of winners and losers from trade have made it increasingly important to look beyond trading values to understand how trade impacts different people, places and firms. Until now, the published UK evidence base has provided limited information on how exporting firms and their employees differ from non-exporting firms.
This paper presents the Jobs in Trade Databasei, a novel dataset that helps address this gap. It separates selected UK business and employee indicators by industry, year and organisation export status, allowing users to compare the exporting and non-exporting parts of industries. Its most distinctive contribution is the ability to examine the characteristics of the employee jobs associated with exporting and non-exporting firms, including differences across sex, age, skill group and earnings.
The database was produced by linking microdata from several major surveys and datasets in the ONS Secure Research Service. This briefing introduces the dataset and presents a selection of example findings with the aim of helping users understand how the data can be interpreted. The full published dataset, alongside the accompanying Methodology and User Guide, is available for users who want to investigate a wider range of indicators, industries and breakdowns.
Research methods
Our results are produced by linking several major datasets produced by either the Office for National Statistics (ONS) or the Northern Ireland Statistics and Research Agency (NISRA).
Data linkage is required because information on trade, economic indicators of businesses, and employee characteristics are held separately. Our project brings these together to create a firm-level dataset that is enriched with firm export status and links through to an employee-level dataset.
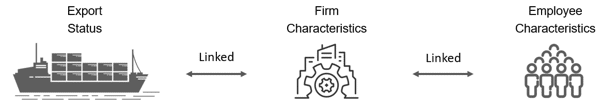
For Great Britain, firm export status is classified based on information in the ONS’ Annual Business Surveyii (ABS) and International Trade in Services Survey (ITIS).iii Most economic indicators are sourced from the ABS and further indicators are introduced using the Annual Purchases Survey.iv Employee characteristics are examined using the Annual Survey of Hours and Earnings (ASHE)v and Business Structure Database (BSD).vi Each firm is classified to an export status on an annual basis, with imputation in non-sampled years.
For Northern Ireland, firm export status is classified using NISRA’s Broad Economy Sales & Export Statistics. Employee totals are sourced from the Annual Business Inquiry. We do not publish comparable economic indicators for Northern Ireland as our investigation of the data led to some quality concerns which we did not have the resources to address.
This report is intended to serve as an initial introduction to the data and some of the results, but we encourage users to read our Methodology and User Guide, which contain key information on assumptions, interpretation and usage.
Example findings
This section presents a small number of example findings from the Jobs in Trade Database. These examples have been selected because they highlight some of the interesting patterns and help demonstrate how the data should be interpreted.
However, they only represent a limited part of what is available. The published dataset contains a much wider range of indicators, industries and breakdowns and users are encouraged to use the data to explore their own areas of interest.
31% of employee jobs in Great Britain worked for exporting firms
Of the 21.1 million full-time equivalent (FTE) employee jobs in Great Britain captured by our dataset for the year 2022, 6.5 million (31%) worked for an exporting organisation.
Directly comparable data for Northern Ireland is not available, but we can examine the annual average of FTE employee jobs from 2018 to 2020. Of the 468k FTE employee jobs captured by our dataset, around 201k (43%) worked for an exporting organisation.
The data can be interpreted as follows:
We estimate that there were 23.9 million FTE employee jobs in Great Britain in 2022. Adjusting jobs into full-time equivalents is a simple adjustment to somewhat account for differences in hours worked between jobs. The adjustment counts a part-time job as half of a full-time equivalent job.
Of these 23.9 million FTE employee jobs, we have assigned 21.1 million to a firm export status of ‘exporter’ or ‘non-exporter’ based on trading information of the employing organisation. The gap of around 2.8 million FTE employee jobs is categorised to the ‘Excluded’ industry and represent jobs in organisations not covered by the underlying data sources, primarily public sector roles in public sector industries, jobs in financial and insurance services or jobs in agriculture. There are similar coverage exclusions for the Northern Ireland data.
Although 6.5 million FTE jobs were in organisations that exported, it is worth bearing in mind that some of these jobs would not have been directly involved in exporting. Many firms that sell to international markets also sell to the domestic market. We plan to produce results that estimate the impact of exporting that takes apportionment into account.
Table 1: Full-time equivalent employee jobs by organisation’s export classification, Great Britain: 2022; Northern Ireland2: 2018-2020 annual average.
| Great Britain | Northern Ireland | |
|---|---|---|
| Exporting organisations | 6,466,434 | 201,444 |
| Non-exporting organisations | 14,663,400 | 266,205 |
| Total known | 21,129,834 | 467,648 |
| Unknown | 2,795,062 | 292 |
| Total | 23,924,896 | 467,940 |
A proportionate shift away from jobs in exporting organisations
Between 2015 and 2022, the number of full-time equivalent (FTE) employee jobs grew by 1.13 million in Great Britain. This comprised a 48k increase in jobs working in exporting organisations, a 689k increase in jobs in non-exporting organisations, and a 389k increase in jobs in our ‘excluded’ category, which contains many public sector roles.
While the job count of each category has grown, this also represents a proportionate shift towards jobs in non-exporting organisations. In 2015, 28.2% of FTE jobs were in exporting organisations. This rises to a peak of 30.4% in 2019 before falling to a trough of 26.5% in 2021 and the series then ending at 27.0% in 2022. Proportions of non-exporting jobs roughly mirrored the inverse of these trends, seeing a peak in 2021 of 62.0%. However, the proportion of non-exporting jobs in 2022 was the same as the start of our series, 2015, with the remaining difference made up by the ‘excluded’ category. We would note that the majority of the excluded category is public sector roles and so would be unlikely to be viewed as exporters through a traditional lens.
Our series cannot determine why jobs have proportionately shifted away from exporting firms. It is possible that recruitment has differed between exporting and non-exporting organisations. These trends correspond with major structural changes in the economy brought on by both the UK leaving the European Union and the impact of the Coronavirus pandemic, which may have weakened employment growth in exporting firms. But it may also be that firms who exported earlier in the series later stopped exporting, therefore shifting their employment from the exporter to the non-exporter classification. Future research will help determine whether these trends continue or return to earlier levels and could also investigate the stability of export classifications.
Figure 1: Proportion of Full-Time Equivalent employee jobs by firm export status, 2015-2022, Great Britain
Jobs in exporting organisations are more likely to be held by men
One of the novel contributions of our new data is an analysis of how personal characteristics differ between roles in exporting and non-exporting firms. Much has been said about the potential “winners” and “losers” from trade, with concerns that negative impacts may be more felt by some groups. Trade can impact our lives in a huge number of ways – here we analyse the relationship between trade and direct employment.
In 2022, 20.4% of female and 32.7% of male FTE jobs were in exporting organisations compared to 67.6% and 55.9% with non-exporters, respectively. Differences between sex appear heavily associated to type of industry. Men are relatively more likely to work in manufacturing industries, and these industries are typically more export-intensive. However, it does also appear that men are also, on average, more likely to work for exporting organisations within a given industry.
We also find that jobs which are classified as lower skilled, or are held by individuals aged 50+, are slightly less likely to work for exporting organisations, although the difference is relatively small.
While men are more likely to work for exporters than women, we find that trends in the labour market have differed between 2015 and 2022, particularly when comparing manufacturing and non-manufacturing industries (Figure 1). We find that, on the whole, the number of jobs in non-manufacturing industries rose between 2015 and 2022, and this occurred in male, female, exporter and non-exporter groups. Over the same period, jobs in manufacturing fell, with close to the entire reduction affecting the male exporter group.
These changes represent a notable shift from manufacturing jobs into services jobs and, particularly, shifts away from jobs in exporting firms in industries such as vehicle manufacturing, which appear to have disproportionately affected men.
Figure 2: Change in Full-Time Equivalent employee jobs by sex, firm export status and industry group, 2015-2022, Great Britain
Jobs in exporting firms earn around 16% more per hour, although differences exist by personal characteristics
We also explore the impact of trade on employment through the wages paid. We examine hourly rather than annual earnings to account for differences in the number of hours worked.
In 2022, jobs in exporting organisations were associated with median hourly earnings of £16.05 compared to £13.87 per hour for non-exporting jobs, a whole-economy premium of 15.7%. While premia differed across industries, it was positive in 38 of 45 industries in 2022, indicating that jobs in exporting firms tend to be paid more than non-exporting firms across the vast majority of industries.
Table 2: Median hourly earnings of employee jobs by organisation export status and employee sex, whole economy, Great Britain, 2022
| Organisation Status | Employee Sex | Median Hourly Earnings (£/hr) |
|---|---|---|
| Exporter | Female | 13.95 |
| Male | 17.37 | |
| Non-Exporter | Female | 13.08 |
| Male | 14.82 |
Jobs held by men saw an exporting premium of 17.2% compared to 6.7% for women across the whole economy.
We believe that a large component of this whole-economy difference is due to employment differences between industries rather than within industries. When looking at the average premium by industry, we found premia of 12.8% for men and 10.7% for women. That is, men working for exporters in a given industry tend to be paid more than men working for non-exporters in the same industry, and women working for exporters in a given industry tend to be paid more than women working for non-exporters. These premia being substantially closer indicates that a large part of the whole economy differential in premia is due to wage and employment differences between industries rather than within industries. However, the female exporter premia remains lower even after averaging across industry.
Table 3: Median hourly earnings of employee jobs by organisation export status and employee age group, whole economy, Great Britain, 2022
| Organisation Status | Employee Age | Median Hourly Earnings (£/hr) |
|---|---|---|
| Exporter | 16-29 | 12.87 |
| 30-49 | 18.13 | |
| 50+ | 16.46 | |
| Non-Exporter | 16-29 | 11.50 |
| 30-49 | 15.54 | |
| 50+ | 13.96 |
Jobs held by 16-29 year olds saw an exporting premium of 11.9% compared to 16.7% and 17.9% for those aged 30-49 and 50+ respectively. Differences did not disappear when averaging across industries, indicating that part of this differential is occurring within industries. However, this comparison was less reliable due to data suppression. We note that there are a handful of industries with very high premia for those aged 30-49 or 50+ but where the premia appear much smaller for the 16-29 age group.
Table 4: Median hourly earnings of employee jobs by organisation export status and employee skill group, whole economy, Great Britain, 2022
| Organisation Status | Employee Skill Group | Median Hourly Earnings (£/hr) |
|---|---|---|
| Exporter | Higher | 20.83 |
| Lower | 11.61 | |
| Non-Exporter | Higher | 18.46 |
| Lower | 10.94 |
Jobs classified as ‘higher’ skilled were associated with an exporting premium of 12.8% compared to a 6.1% premium for ‘lower’ skilled jobs. The average premium by industry was 16.0% for higher-skilled and 5.1% for lower-skilled jobs, showing that within-industry differences in premia are relatively large.
When interpreting these figures, it is important to recognise that these results do not indicate causality. For example, they cannot indicate whether a firm becoming an exporter has access to more international demand for its products and may pay higher salaries as a result or instead the firm pays higher salaries because the types of businesses that export tend to be more productive regardless. Our results instead provide a strong set of descriptive data at a granular industry level for a broad range of indicators, which provides a useful basis for identifying these differences before further investigation.
Exporting firms, as a whole, are more productive per job but produce less GVA per unit of output
In 2022, exporting firms made up just over half (50.8%) of output, a concept similar to turnover, while employing under a third (30.6%) of full-time equivalent employee jobs (Table 5).
Table 5: Proportion of indicator by firm export status, 2022, Great Britain
| % of total indicator | ||
|---|---|---|
| Indicator | Exporters | Non-exporters |
| Output | 50.8% | 49.2% |
| FTE Employee Jobs | 30.6% | 69.4% |
| Intermediate consumption | 54.5% | 45.5% |
| Net capital expenditure | 47.1% | 52.9% |
| GVA | 47.0% | 53.0% |
| Employment costs | 49.5% | 50.5% |
| Gross wages | 48.6% | 51.4% |
| Taxes less subsidies on production | 42.0% | 58.0% |
| UK purchases* | 52.7% | 47.3% |
| International purchases* | 84.4% | 15.6% |
* 2021-22 average
In line with other research, we find that exporting firms are more productive on a Gross Value Added (GVA) per Full-Time Equivalent (FTE) employee job basis. Economy-wide, an FTE employee job in an exporting firm was associated with £118k GVA compared to £59k GVA in a non-exporting firm.
Table 6: Value of indicator associated with each FTE employee job, 2022, £ thousand, Great Britain
| £ thousand per FTE employee job | ||
|---|---|---|
| Indicator | Exporters | Non-exporters |
| Output | 257 | 110 |
| GVA | 118 | 59 |
| Employment costs | 64 | 29 |
| Gross wages | 54 | 25 |
Excluding “Excluded” industry FTE employee jobs.
Corresponding with the higher median hourly earnings shown earlier, average employment costs across all exporting firms stood at £64k per FTE employee job compared to £29k for non-exporting firms. Note that this wage data reflects mean rather than median wages, and our simple approach to converting part-time jobs into FTE jobs means that these will not match national statistics.
Per job, exporting firms produce disproportionate amounts of output, are highly productive and pay both higher median hourly earnings and total employee costs.
However, this can also be framed differently (Table 7). As a proportion of output, exporting firms contribute relatively lower GVA, spend proportionately less on Net Capital Expenditure, spend relatively more on inputs of goods and services, and spend less on total employment costs. Some of these may come as a surprise to even a seasoned trade economist but they are not in disagreement with the earlier results.
For example, exporting firms can produce more GVA per job and afford to pay higher wages as a result, but the total employment cost for the firm may still be smaller than a comparable non-exporter that employs a greater number of less productive jobs. The income approach to GVA shows that GVA is the sum of employee compensation, Gross Operating Surplus and taxes less subsidies on production. As taxes less subsidies on production are a very small contributor to GVA, this leads us to conclude that GVA per unit of output differs partly because of a lower total wage bill and partly because of lower Gross Operating Surplus (e.g. lower profits) for a given level of output.
This difference is mostly driven by industry. While the whole economy difference in GVA as a percentage of output is 7.5 percentage points, the average difference across industries is 1.4 percentage points and the median difference is 1.9 percentage points. This still implies that non-exporting firms tend to have higher GVA associated with each unit of output but also indicates the importance of granular industrial breakdowns, as provided in our data.
Table 7: Indicator by export group as a proportion of corresponding output, 2022, Great Britain
| % of total output | ||
|---|---|---|
| Indicator | Exporters | Non-exporters |
| Intermediate consumption | 54.2% | 46.7% |
| Net capital expenditure | 5.2% | 6.0% |
| GVA | 45.8% | 53.3% |
| Employment costs | 24.8% | 26.2% |
| Gross wages | 20.9% | 22.8% |
| Taxes less subsidies on production | 0.8% | 1.2% |
| UK purchases | 29.9% | 27.7% |
| International purchases | 7.6% | 1.5% |
Another major difference between exporters and non-exporters can be found in their propensity to purchase international goods and services. It is unsurprising that exporting firms have more international supply chains, but our research shows that as much as 84% of the value of international purchases was made by exporting firms compared to 16% by non-exporting firms in 2021-2022. Put in other terms, each unit of output by an exporter is associated with around five times more spent on international purchases than in non-exporting firms. This indicates the importance that imports play in the exports of UK goods and services.
Conclusion and next steps
The Jobs in Trade Database provides a new evidence base for understanding how exporting firms and their labour force differs from non-exporting firms, and how these patterns vary across workers, industries and economic indicators. The findings in this Briefing Paper show that exporting is associated with a substantial share of employment, higher median hourly earnings and higher productivity per job, while also highlighting important differences by sex, age, skill group and industry.
Work is already underway to use these results to disaggregate the industries in the ONS’ UK Industry-by-Industry Input-Output Table into exporters and non-exporters. This will allow us to assess not only the jobs and activity directly associated with exporting firms, but also the wider supply-chain impacts supported by exporters across the UK economy. This matters because trade affects many people who do not work directly for exporters through the firms that supply exporters and the workers employed in those supply chains.
Footnotes
- Access the dataset, methodology and user guide: https://doi.org/10.5255/UKDA-SN-858696
- Northern Ireland values are suppressed for the ‘Excluded’ industry. The numbers presented here are estimated using author’s calculations.
Endnotes
i. Black, James and Fox, Calum and Spowage, Mairi (2026). Jobs in Trade Database: Business and Employee Indicators by Firm Export Status and Industry, 2011-2022. [Data Collection]. Colchester, Essex: UK Data Service. https://doi.org/10.5255/UKDA-SN-858696
ii. Office for National Statistics, 2025, ONS SRS Metadata Catalogue, dataset, Annual Business Survey - GB, https://doi.org/10.57906/ks2s-qx24
iii. Office for National Statistics, 2025, ONS SRS Metadata Catalogue, dataset, Annual International Trade in Services - UK, https://doi.org/10.57906/d42y-c117
iv. Office for National Statistics, 2023, ONS SRS Metadata Catalogue, dataset, Annual Purchases Survey - UK, https://doi.org/10.57906/zd3q-d088
v. Office for National Statistics, 2025, ONS SRS Metadata Catalogue, dataset, Annual Survey of Hours and Earnings - GB, https://doi.org/10.57906/x25d-4j96
vi. Office for National Statistics, 2025, ONS SRS Metadata Catalogue, dataset, Business Structure Database - UK, https://doi.org/10.57906/7kh0-0910
Author Profiles
James Black